Why every Chief Collection Officer needs a Digital ID Management Platform, not just an ID card
Collection and recovery work is a people business. Banks, NBFCs, FinTech companies and Co-operative Banks rely on field executives and third-party recovery agents to meet customers face to face, often at their homes or offices. That direct contact is exactly why agent identity, authorization and verification matter so much.
A laminated ID card used to be enough. It isn't anymore. When a collection team has thousands of agents spread across cities, a plastic card can't tell a customer whether the person at the door is still employed, still authorized, or even genuine. A Digital ID Management Platform like MeCard is built to answer that question in seconds.
Collection and recovery operations have one of the highest turnover rates in financial services. Agents join, leave, switch agencies, or move cities every month. Each change triggers a chain of manual work: printing, dispatch, activation, surrender and deactivation. Any delay in that chain creates real operational risk.
A new agent needs identity checks, approval and a printed card before they can start field visits. An exiting agent needs their old card physically collected and invalidated. When hundreds of agents move in and out every quarter, this process becomes hard to track manually.
A typical physical card moves through creation, approval, printing, dispatch, delivery, activation and eventually surrender. A delay at any point either stalls a ready agent or leaves an inactive card usable in the field. Neither outcome is acceptable in a regulated collection environment.
PVC cards, printing consumables, courier charges, reprints for lost cards and reprints for address or designation changes all add up. For an organization issuing thousands of cards a year, these recurring costs are significant and largely avoidable.
Mobile numbers, branches, designations and employment status change often. A physical card frozen at the moment of printing can't reflect any of that, so customers may end up looking at outdated details.
HR, collections, operations, admin and printing vendors all need to coordinate for every card issued. That coordination pulls people away from the actual work of collections and recovery.
Beyond cost and convenience, there's a sharper problem. Physical cards can be lost, copied, altered or used well after an agent has exited the organization. For a customer standing at their own front door, this isn't an administrative detail — it's a fraud risk.
A customer should be able to ask simple questions and get real answers: Who is this person? Which company do they represent? Is their ID currently active? Can I verify this independently, without relying only on what the agent tells me?
Every customer interaction is also a brand interaction. When verification is weak, trust weakens with it — and in collections, trust is the difference between a resolved account and a complaint.
MeCard helps Banks, NBFCs, FinTech companies and Co-operative Banks move away from treating an ID as a piece of plastic and toward treating it as a controlled, verifiable identity system.
Instead of the old print-dispatch-surrender-reprint cycle, MeCard lets collection teams create, verify, update, control, block and audit agent identities from one dashboard.
New agents can be issued a digital ID quickly. Approved details can be updated centrally the moment something changes. When an agent exits or is no longer authorized, their ID can be blocked instantly, without waiting for a physical card to be returned.
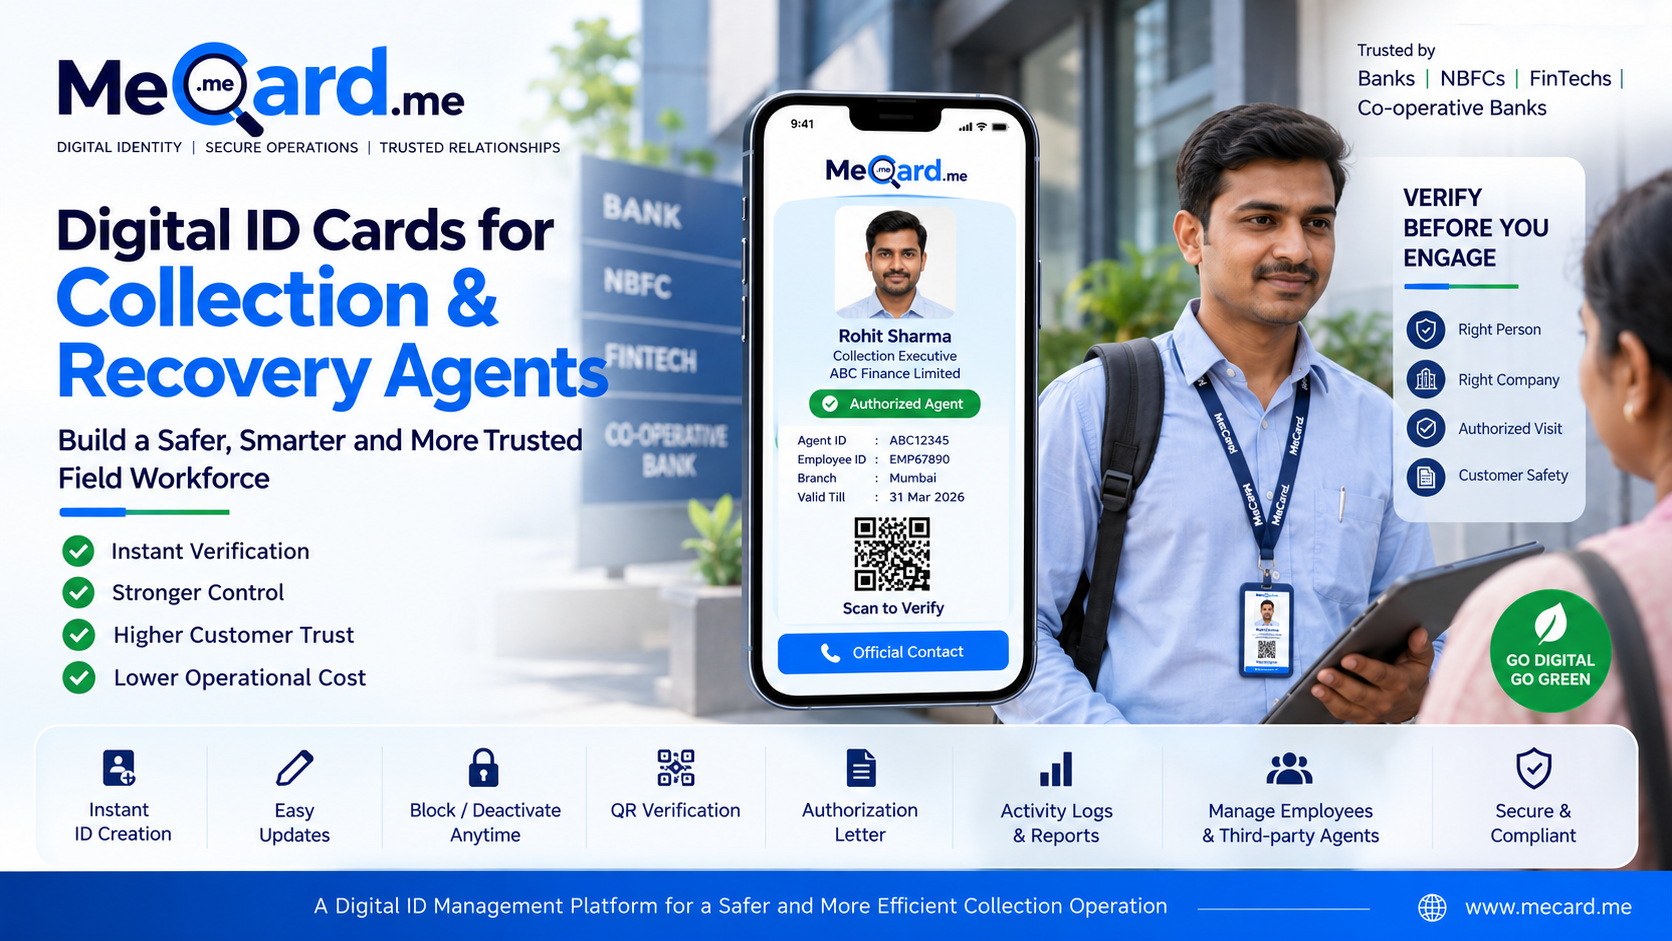
Every MeCard digital ID carries a QR code. A customer scans it with any smartphone camera and lands on the agent's verified digital profile — no app download required. It's the same instant-verification idea that makes MeCard's business card platform work for sales teams, applied to a higher-stakes setting.
An agent's digital profile can carry their authorization information alongside their identity, so a customer sees not just who someone is, but the authority under which they're visiting.
Administrators get a live view of active, inactive and blocked agents. When someone leaves the organization or an agency contract ends, deactivation happens centrally instead of depending on a card being handed back.
Every creation, update, activation, deactivation and block is logged. That record supports internal monitoring, investigations and audit requirements without extra manual paperwork.
Customers get access to official company contact information on the digital profile itself, so they aren't limited to the mobile number the field agent happens to give them.
Agent and employee data is sensitive. MeCard supports a controlled approach to managing this information, including access control, centralized data management, defined user permissions and auditability. That structure helps organizations strengthen their approach to applicable Digital Personal Data Protection requirements, though every institution should still assess this against its own regulatory obligations.
A digital-first model reduces dependence on PVC printing, consumables, courier dispatch and reprints caused by lost cards or changed details. For an organization managing a large field workforce, even a modest saving per agent adds up to a meaningful figure across a year.
MeCard helps collection teams shift from managing plastic cards to managing verified digital identities — with instant creation, QR-based verification, centralized control and full audit trails.
The traditional model looks like this: company issues a physical ID to an agent, and the customer has almost no way to independently check it. The digital model looks different: company issues a digital ID, the customer scans a QR code, and verification happens on the spot.
That shift creates a genuine trust layer between the institution, the agent and the customer — something a laminated card was never designed to do.
MeCard's Digital ID Management Platform is built for Chief Collection Officers, Heads of Collections and Recovery, Collection Operations Heads, Chief Compliance Officers, Risk Heads, Digital Transformation Heads, HR & Operations Heads and Customer Experience Heads across Banks, NBFCs, FinTechs, Co-operative Banks, Housing Finance Companies and Microfinance Institutions.
The real question for a modern collection team isn't whether to replace a PVC card. It's whether the organization can centrally control, verify and audit the identity of every person representing it in front of a customer. MeCard's Digital ID Management Platform gives Banks, NBFCs, FinTechs and Co-operative Banks exactly that — faster onboarding, lower administrative effort, better agent control, stronger customer verification and a clearer audit trail, all from one platform.
If your organization manages hundreds or thousands of collection and recovery agents, physical ID administration is likely costing more than it should. MeCard helps you move from ID-card paperwork to centralized digital identity management — create, verify, update, control and block, all in one place.
It's a centralized system for creating, verifying, updating and deactivating employee or agent identities digitally, replacing manual, print-based ID card processes.
MeCard lets banks and NBFCs issue digital IDs to field agents instantly, verify them through a QR code, and block them the moment an agent exits — without relying on physical card surrender.
Yes. The customer scans the agent's QR code with a smartphone camera and is taken directly to the agent's verified digital profile, including official company contact details.
Yes. Administrators can create, update and manage large volumes of agent IDs from a single dashboard, which is useful for organizations with thousands of field employees or third-party agents.
Their digital ID can be blocked or deactivated centrally and instantly, instead of depending on the physical card being returned.
MeCard supports a controlled approach to agent data, including access control, centralized management and audit logs, which can help organizations strengthen their DPDP-related practices. Institutions should still assess this against their own specific regulatory obligations.
Yes. MeCard can manage identities for both in-house field employees and agents from third-party collection and recovery agencies under one centralized system.
Yes. Moving away from PVC card printing, courier dispatch and reprints for lost or outdated cards can meaningfully reduce recurring costs for large field teams.
Phone: +91 77770 01366 / +91 77770 01369
Email: contact@mecard.me
Website: www.mecard.me
Sanjay Maurya, Director, Digital Business Technology Pvt. Ltd.
Phone: +91 98338 87284
Email: sanjay.maurya@dbtpl.com